A note on scope: Wealthlab no longer provides SMSF establishment, administration or advice services, which we exited in 2026. This article is general commentary on the rule changes for anyone affected by them. For SMSF-specific decisions, speak with a licensed SMSF specialist or your accountant. Where SMSF questions connect to the bigger retirement picture, that is where we can help.
2026 has been the biggest year for SMSF rule changes since borrowing was first allowed in 2007, and the picture has shifted again in just the past three months. The residential property borrowing ban is no longer coming, it is in force, with the window having closed on 10 August 2026. The $3 million super tax (Division 296) started on 1 July 2026 in its final, redesigned form. And on 19 August, the government announced a further package of proposed SMSF reforms that trustees will want on their radar.
Here is what has actually changed, what survived intact and what is still only a proposal, in plain English.
The residential borrowing ban is now in force
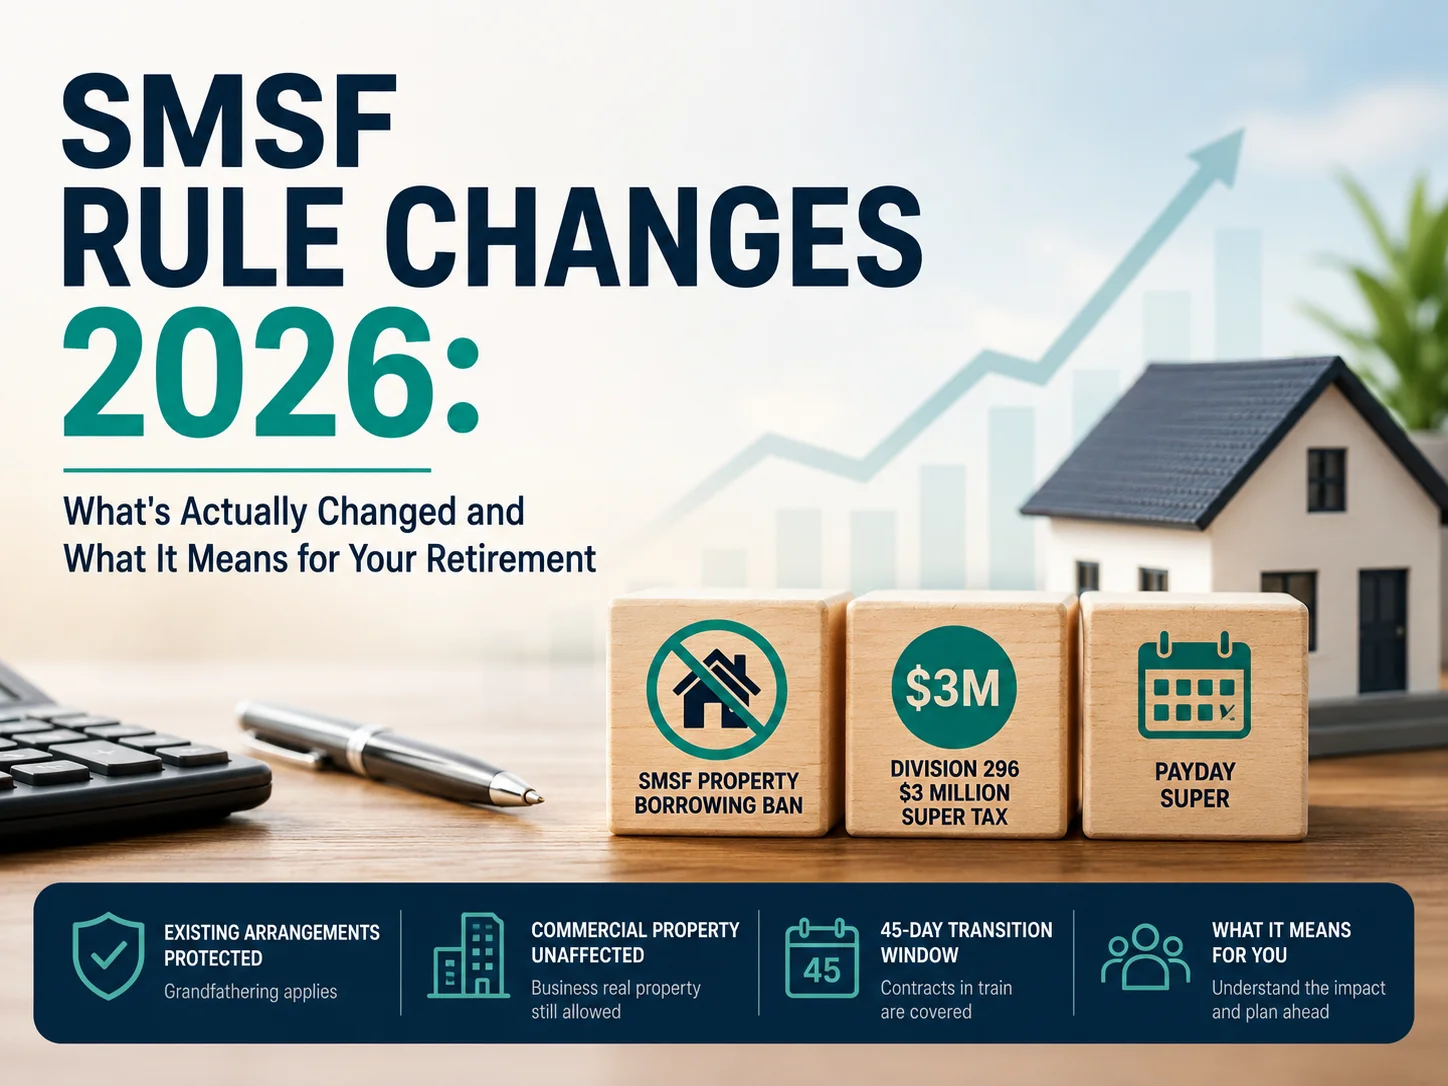
Since 10 August 2026, SMSFs can no longer enter a new limited recourse borrowing arrangement (LRBA) to buy residential property. New LRBAs over real property are only permitted where the asset is business real property, meaning property used wholly and exclusively in a business, such as commercial, industrial or qualifying farm property. The change came as part of the same Act that overhauled the CGT discount, after a deal between the government and the Greens announced on 23 June. Source: ATO, changes to limited recourse borrowing arrangements. Current as at September 2026.
What the ban does not do matters just as much:
Existing residential LRBAs are grandfathered. A fund already holding residential property under an LRBA keeps the arrangement, keeps making repayments and faces no forced sale. Refinancing an existing LRBA remains available.
Contracts exchanged before 10 August are protected. The ATO’s guidance (published 28 July 2026) confirms a fund that exchanged a binding contract before the deadline can settle and enter the LRBA afterwards without breaching the rules.
Buying residential property outright is still allowed. The ban is on borrowing, not on residential property itself. A fund with sufficient cash can still purchase within the usual investment rules.
The test is the definition, not the label. The law bans new LRBAs over anything that is not business real property. In limited cases a residential property used wholly and exclusively in a business can meet that definition and remain financeable, and it must keep meeting it for the life of the loan. That is specialist territory, not a loophole to lean on.
For anyone whose retirement strategy leaned on gearing residential property inside super, the strategy is closed to new entrants. That is a planning question more than an SMSF administration question, and it is worth revisiting the overall plan rather than hunting for workarounds.
[IMAGE: existing SMSF.webp. Change alt text to: “SMSF borrowing ban and Division 296 changes in 2026”]
Division 296: the $3 million super tax is now running
The second change is bigger for more people over time. Division 296 became law in March 2026 and applies from 1 July 2026, adding extra tax on the earnings attributable to very large super balances. The final design differs meaningfully from the version that caused the original uproar:
Only realised earnings are taxed. Interest, dividends, rent and capital gains on assets actually sold. Unrealised paper gains, the most criticised feature of the original proposal, were dropped from the final law, and gains accrued before 1 July 2026 are excluded.
Two indexed thresholds. Earnings attributable to the portion of a total super balance above $3 million attract an extra 15% (an effective 30% on that slice). A second threshold at $10 million adds a further 10% (an effective 40% above it). Both thresholds are indexed with the Transfer Balance Cap, in $150,000 and $500,000 increments respectively.
It is assessed to the person, not the fund. The tax applies whether the money sits in an SMSF, industry fund or retail fund, with no SMSF-specific carve-out or extra penalty, and it can be paid personally or released from super. The first measurement point is 30 June 2027, with the first assessments expected in 2028.
A simple illustration of the scale: a member with a $4 million total super balance whose fund attributes $200,000 of realised earnings to them for the year would see roughly a quarter of those earnings (the proportion of the balance above $3 million) attract the extra 15%, an additional tax bill in the order of $7,500.
Please note: All figures, projections and scenarios in this article are approximate and for illustrative purposes only. Individual outcomes will vary based on personal circumstances, asset values, fund earnings and current government policy. This is general information, not personal advice.
For SMSF trustees specifically, Division 296 raises the stakes on two perennial weak spots: asset valuations (30 June balances now directly drive a personal tax outcome, so lazy valuations invite scrutiny) and liquidity (a fund holding one big illiquid asset has fewer options for paying or managing the tax). There was also a one-off option to reset the cost base of certain assets to market value as at 30 June 2026, which is precisely the kind of detail to run past your accountant rather than a blog.
What didn’t change for SMSFs (and one quiet win)
Amid the noise, some things worth knowing stayed put or improved:
Super funds are excluded from the CGT overhaul. The reform replacing the 50% CGT discount with indexation from 1 July 2027 applies to individuals, trusts and partnerships, not superannuation funds. SMSFs keep their existing CGT treatment, which quietly improves the relative position of assets held inside super compared with the same assets held personally after mid-2027.
The caps moved up. The concessional contributions cap is $32,500 for 2026-27 and the non-concessional cap is $130,000, with a bring-forward maximum of $390,000, subject to balance limits. The Transfer Balance Cap rose to $2.1 million on 1 July 2026. Source: ATO key superannuation rates and thresholds. Current as at September 2026.
The August proposals: not law yet
On 19 August 2026, the government announced a further package of proposed SMSF reforms covering, among other things, tighter expectations on written investment strategies, a new SMSF share of the regulatory sector levy and requirements for fund assets to be uniquely identifiable. These are proposals, not law. Current rules continue to apply, and the final design could change considerably through consultation. The sensible posture is awareness, not action: trustees who already maintain a genuine, documented investment strategy and clean separation of fund assets are largely doing what the proposals point toward anyway.
What this means in practice
We generally find the SMSF conversations that matter in 2026 are less about the rules themselves and more about whether the structure still earns its keep. An SMSF makes sense when the control genuinely gets used and the costs and trustee obligations are carried comfortably. The changes this year tilt the calculus for some people: the borrowing route into residential property is gone for new arrangements, large balances now carry extra tax wherever they sit, and the compliance bar keeps inching up.
Scott and Phil have touched on one recurring SMSF trap on the podcast: property-heavy funds and liquidity. A fund whose wealth is mostly one building can struggle when pension payments, tax bills or member exits demand cash, because you can’t sell a bedroom to cover this year’s pension payments. Division 296 only sharpens that issue for larger funds. They dug into it on the episode about preservation age and SMSF liquidity, which is worth a listen:
For the trustee obligations themselves, your SMSF specialist and accountant are the right people. For the question underneath, whether the fund still fits the retirement you are planning, that is squarely our territory via retirement planning. The broader system these rules sit inside is covered in How retirement works in Australia.
Frequently asked questions
Can an SMSF still borrow to buy residential property?
Generally no. Since 10 August 2026, new limited recourse borrowing arrangements over real property are only allowed for business real property, and most residential property does not meet that definition. Existing residential LRBAs are grandfathered, contracts exchanged before the deadline are protected and refinancing existing arrangements remains available.
Does my SMSF have to sell its residential property?
No. The ban applies to new borrowing arrangements only. Funds already holding residential property, geared or outright, are not required to sell, and outright purchases of residential property (without borrowing) remain permitted under the usual investment rules.
What is Division 296 and who pays it?
An extra tax on the earnings attributable to the portion of an individual’s total super balance above $3 million (an effective 30% on that slice, rising to 40% above $10 million). It applies from 1 July 2026 to realised earnings only, is assessed to the individual regardless of fund type, and both thresholds are indexed.
Does Division 296 tax unrealised gains?
No. The final legislation dropped the taxation of unrealised gains. Only realised earnings count: interest, dividends, rent, distributions and capital gains on assets actually sold. Gains accrued before 1 July 2026 are also excluded.
Did the CGT discount changes affect SMSFs?
No. The replacement of the 50% CGT discount with indexation from 1 July 2027 applies to individuals, trusts and partnerships. Superannuation funds, including SMSFs, keep their existing CGT treatment.
Are more SMSF changes coming?
Possibly. A reform package proposed on 19 August 2026 covers investment strategy standards, a sector levy and asset identification requirements. None of it is law yet, and current rules continue to apply while consultation runs.
Where to take it from here
Wealthlab doesn’t provide SMSF services, so we won’t be setting up, administering or winding up a fund for you, and the trustee-level detail belongs with your SMSF specialist and accountant. What we do every day is help people work out whether their current structures, SMSF included, still serve the retirement they actually want.ether their current structures, SMSF included, still serve the retirement they actually want.If this year’s changes have raised that bigger question, have a chat with us. No pressure, no jargon.
If any of this has raised questions about your own super or SMSF, book a free chat with the Wealthlab team. No pressure, no jargon, just a conversation about whether your current setup still fits where you’re heading.
Not sure where you stand? Take the free Wealthlab retirement quiz for a quick snapshot.